Housing
New construction vs resale in Ocala
In most markets this is a taste question. In Florida it is partly an insurance question, and that changes the arithmetic enough to be worth working through.
Bottom line
- A new roof is an insurance asset in Florida, not just a maintenance saving. Roof age is often the first underwriting question, and on that one line new construction starts well ahead.
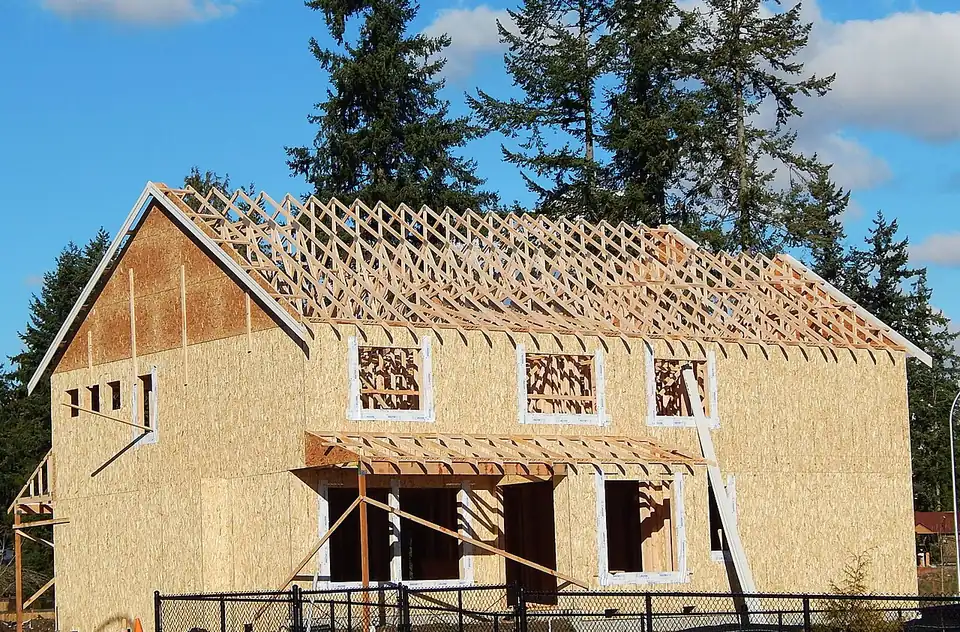
- Marion County issued 5,985 building permits in 2025 while the county grew 17.8 percent in five years, so new supply is a real part of this market rather than a niche.
- Resale buys you established trees, a known neighbourhood, a septic and well you can inspect, and a seller who can be negotiated with. New construction buys you a warranty, current code and no deferred maintenance.
Marion County issued 5,985 building permits in 2025 against a housing stock of 205,732 units, in a county that grew 17.8 percent between the 2020 census and mid-2025. New construction is not a sideshow here. For a lot of buyers arriving from out of state it is a real alternative to the resale market, and the comparison is more interesting in Florida than it is in most places.
The line that makes Florida different: insurance
In most of the country, "the roof is newer" is a maintenance point. In Florida it is an underwriting point, and sometimes a binary one.
Florida insurers price roof age, roof covering, roof deck attachment, roof-to-wall connection, roof geometry and opening protection. Section 627.711 of the Florida Statutes requires them to tell you what discounts are available for those windstorm mitigation features. A house built to current code with a new roof typically has more of those features and documents them more easily.
The practical shape of that:
- New build: roof at year zero, current code, likely good mitigation scores.
- Resale, roof under ten years old: generally fine, get the wind mitigation inspection and the roof documentation.
- Resale, roof approaching or past twenty years: this may be the decision. Depending on material and carrier, you may face replacing it, accepting depreciated coverage on the roof, or being unable to get a policy at a price that works.
None of that makes resale a bad idea. It makes the roof the first question you ask about any resale in this state, before the kitchen, before the school zone, before anything. What actually drives your Florida home insurance premium goes through the rest.
What resale actually gives you
Trees. This matters more in Marion County than it sounds. The live oaks are the reason the county looks the way it does, and a mature canopy is a thirty-year asset that no amount of money buys new. A new subdivision's landscaping is somebody's first-year planting.
A neighbourhood you can observe. Drive it at eight in the morning, at six in the evening, and on a Saturday. What is it like? You cannot do that on a street that does not exist yet.
Systems you can inspect. A well and a septic system that have been in operation can be tested and evaluated. So can a roof, an air handler and an electrical panel. You are buying a known quantity with known problems, and known problems are cheaper than unknown ones.
A seller who can move. One household making one decision about one house. There is genuine negotiation available: on price, on repairs, on timing.
Location that is already built out. Established parts of the county are near things because the things came first.
Immediate occupancy. Close, move in. No construction schedule.
What new construction actually gives you
Current code. Florida's building code has been strengthened repeatedly since Hurricane Andrew. A house built to it is a different structure from one built to the 1980s version, particularly in wind resistance.
A warranty. Structural and systems coverage for a defined period, which is not the same as "nothing will go wrong" but is meaningfully different from resale, where the house is yours the moment you close.
No deferred maintenance. Nobody has put off the roof, the water heater or the drainfield. That is worth a real number in the first five years.
Efficiency. Current insulation and window standards against an older house's, in a climate where cooling runs for most of the year. Florida households already average more electricity than the national figure; an inefficient envelope makes that worse.
Selection, if you are early enough. Layout and finishes, within what is offered.
The things that are not obvious
Wells and septic are not an age question here. Large parts of Marion County are on private wells and onsite sewage systems, and that includes plenty of new construction. Do not assume a new house is on public water and sewer — ask about the specific address. A well and a septic system are perfectly normal here and they come with their own maintenance, their own testing and their own siting rules.
Property tax will surprise both kinds of buyer, differently. On a resale, the seller's tax figure is usually their homesteaded, Save Our Homes-capped number and has nothing to do with what you will pay. On a new build, the first assessment may be on land only, and the first full assessment after the house exists is a different number. Both traps are the same trap: use the estimator with your own numbers, and read Marion County property taxes explained.
Flood zone applies to both. New construction in a mapped zone is still in a mapped zone. Check FEMA's map either way.
Timelines run opposite. Resale is fast and then finished. New construction is slow, and the slow part is before you own anything — which is fine if you are renting and terrible if you have already sold somewhere else. Renting first vs buying is the same decision from the other side.
Which one, then
Reasonable defaults, not rules:
- New construction if insurance cost is a live constraint, if you want a warranty rather than a project, if your timeline is flexible, or if you are arriving from out of state and do not yet know the county well enough to judge a specific street.
- Resale if you want mature trees and an established location, if you are comfortable evaluating a house's condition, if you want negotiating room, or if you need to be in a house next month.
And in both cases the same three questions decide whether the deal is good: the roof, the flood zone, and what the tax bill will actually be under your name. Everything else is preference.
Neither route is examined on this site with a thumb on the scale for the other; the disclosure under the block below says plainly where the owner's commercial interest lies, which is why that block is there.
Sources
- U.S. Census Bureau QuickFacts — Marion County, Florida — 5,985 building permits in 2025; 205,732 housing units as of July 2025; median value of owner-occupied housing $243,100; owner-occupancy 77.5 percent; population growth 17.8 percent from 2020 to 2025. ACS figures are 2020-2024 five-year estimates in 2024 dollars (retrieved September 18, 2026)
- Florida Statutes section 627.711 — Notice of premium discounts for hurricane loss mitigation — insurers must disclose the discounts available for windstorm loss mitigation features (retrieved September 18, 2026)
- Florida Office of Insurance Regulation — the regulator for Florida property insurance (retrieved September 18, 2026)
- Florida Department of Health — Onsite Sewage Programs — septic system permitting and standards in Florida (retrieved September 18, 2026)
- Florida Department of Health in Marion County — county-level well and septic permitting and records (retrieved September 18, 2026)
- FEMA Flood Map Service Center — flood zone determination, which applies to new and existing construction alike (retrieved September 18, 2026)
Common questions
Is it cheaper to buy new or resale in Ocala?
Price per square foot usually favours resale; total cost of ownership in the first years often favours new, because the roof, the systems and the code compliance are new and the insurance reflects that. The honest answer is that they are different products and comparing them on price alone misses the lines that actually differ — insurance, repairs, warranty, and what you have to do to the house in year one.
Does new construction cost less to insure in Florida?
Generally yes, and the reason is specific rather than general. Florida insurers price roof age, roof attachment, construction type and opening protection, and a house built to current code with a new roof scores well on all of them. Section 627.711 of the Florida Statutes requires insurers to disclose the discounts available for windstorm mitigation features, and a new build typically has more of those features to document.
Do new homes in Marion County have wells and septic?
Many do, and many do not — it depends entirely on where in the county the parcel is. Large parts of Marion County are on private wells and septic systems rather than public water and sewer, and that is true of new construction as well as of older houses. It is a question to ask about a specific address rather than to assume from the age of the house.
What is deferred maintenance and why does it matter more here?
Work an owner has put off: the roof, the air conditioner, the water heater, the septic drainfield. It matters more in Florida because two of those items are both expensive and insurance-relevant. A twenty-year-old roof is not merely an upcoming cost, it is potentially the reason a carrier declines to write the policy at all.
Can you negotiate on new construction?
There is usually less movement on the headline price and more on what is included, on closing cost contributions and on finishes — because a price reduction affects the comparable sales for everything else being sold nearby and an incentive does not. On a resale you are negotiating with one household about one house, which is a genuinely different conversation.